Licensed in Washington · License # 1232824
Storm Damage Claims in Western Washington
Pacific windstorms lift shingles, push rain under flashing and loosen siding in ways you cannot always see from the yard. We represent you, not the insurer. We document it all and press for a settlement that pays for the repair.
Direct line to our Aberdeen, WA team: 360-300-7366
Open 24/7. Residential homeowners only. Nothing upfront.
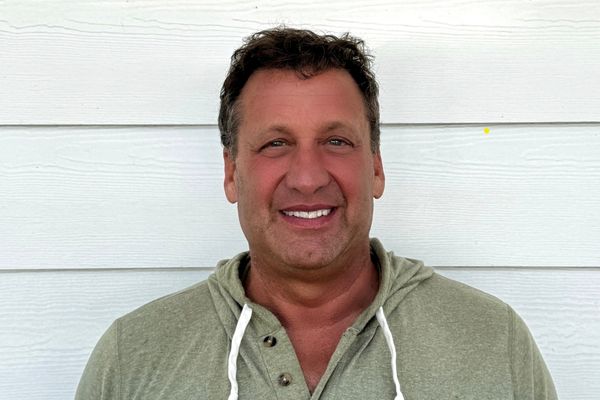
“We deal with the insurer, so you can focus on your home.”
Matt Hultman, Owner
- LicensedWashington license # 1232824.
- LocalLed by Matt Hultman, with a local Aberdeen, WA team.
- Nothing upfrontPaid a percentage of the settlement, under a written contract.
What we do for you on a storm claim
After a big windstorm, insurers and roofers are stretched thin. We keep your claim moving.
We check the policy
We look at how it treats wind, rain and roof damage, and how the deductible applies.
We inspect inside and out
We go over the roof, siding and windows, then the attic and the rooms below.
We document and price it
Each repair is listed and priced, from a few lifted shingles to a full roof section.
We handle the insurer
We file the claim, meet the adjuster and negotiate for you.
Open 24/7. Call as soon as the wind dies down.
Stuck with your insurer? Read what homeowners say about working with us.
G★★★★★5.0 from 12 Google reviews“I had a very positive experience working with Washington Public Adjusters… After months of going back and forth with our insurance company without any progress, we were feeling frustrated and stuck.”
Cynthia · Google review
Read Cynthia's review on Google“Excellent experience with Washington Public Adjusters, after a fire at my home Allstate gave me only 10% of what it was going to cost for repairs.”
Gretchen · Google review
Read Gretchen's review on Google“Matt at Washington Public Adjusters was amazing to work with. He really cares about his customers and not afraid to go the extra mile to get the job done.”
Christy · Google review
Read Christy's review on GoogleHow we help you get the money you deserve
Storm estimates tend to cover the damage that is easy to point at. Much of it is not.
What a quick inspection misses
- Shingles and flashing that lifted in the wind but look fine from the ground
- Rain that reached the attic, insulation and ceilings
- Damaged siding, windows, gutters and fascia
- A repair that will not blend with the rest of the roof or siding
How we get the claim paid
- We build the full scope, file it and negotiate with the insurer's adjuster so you do not have to.
- No money is due upfront. We take an agreed percentage of the settlement, set in a written contract.
- Residential homeowners only. A storm claim usually takes at least 3 months to resolve.
- For repairs, use our trusted local contractor directory or pick your own.
How it works
What happens after you call about storm damage.
Call when it is safe
Tell us what the storm did. We answer at any hour.
We check the exterior
We inspect the roof, siding, windows and attic, then the rooms underneath.
We build and file the claim
We begin with a written contract, then prepare the full scope and file it.
We negotiate, you repair
We work the claim while you schedule the work. Plan on at least 3 months.
What a storm claim can include
Every policy differs. This is what we usually document.
Roof covering
Shingles, underlayment and decking that wind lifted, creased or tore away.
Flashing, vents and gutters
Small parts that let water in when they shift, and that are easy to overlook.
Siding, trim and fences
Panels blown loose or cracked by flying debris, plus fence sections that went down.
Windows and doors
Broken glass, damaged frames and seals that now leak in the rain.
Attic and interior water
Wet insulation, stained ceilings and soaked walls from rain that got in.
Temporary repairs
Tarps and board-up that keep more rain out. Save every receipt.
What to do after the windstorm
- Stay clear of hazards. Watch for downed lines, broken glass and hanging limbs. Report them to your utility or 911.
- Photograph inside and out. Take wide and close shots of every damaged area.
- Do not climb a damaged roof. Use a zoom lens or ask us to inspect it.
- Cover the openings. Tarp the roof or board up a window, and keep the receipts.
- Write down the timeline. Note when the storm hit and when you first saw each problem.
- Be careful with door-knockers. Do not sign a repair contract until you know what your claim covers.
- Call us. We are open 24/7, including the night of the storm.
Why storm claims get underpaid
The roof is checked from below
A look from the ground misses lifted shingles, cracked sealant and bent flashing.
Repair is offered, not replacement
A few shingles get patched where the roof's condition calls for more.
Rain damage is split off
Attic and ceiling damage may be treated as separate from the roof opening.
Wind damage is called wear
An insurer may blame age for what the storm did. Documentation separates the two.
Small items go uncounted
Fascia, vents, gutters and fences are small alone and meaningful together.
Wind first, then rain
Pacific storms hit with wind and follow with hours of soaking rain. Wind opens the roof, and rain does the work inside, often before anyone is on site.
If a tree caused the damage, see our fallen tree damage claims page. It covers removal and structural damage in detail.
Keep any pieces that blew off, such as shingles or trim, until the claim has recorded them.
Repair or replace the roof?
This question decides many storm claims. Age, the number of damaged areas and whether new shingles can blend with the old all play a part.
We document the roof as a whole, not just the spots the adjuster marked, so the discussion is about facts instead of a quick look.
Photograph the roof lines and flashing the same way, so the adjuster sees what you see.
Storm damage claim questions
Does homeowners insurance cover wind and rain damage?
Wind damage to a home is generally a covered loss, and rain that enters through a storm-made opening often is too. The details are in your policy. We read it and tell you what applies.
Will my insurer replace the roof or only repair it?
That depends on the roof's condition, the extent of the damage and your policy. We document the whole roof and make the case for the repair it needs.
A tree hit my house in the storm. Is that a storm claim?
It starts with the same storm, but tree damage raises its own questions, such as removal and whose tree it was. Our fallen tree page covers them, and we can handle the claim together.
Should I wait for the adjuster before making temporary repairs?
No. Cover openings and stop leaks now, and photograph the damage first. Keep the receipts for tarps and board-up.
The insurer says the damage is wear and tear. Can you help?
Yes. We document the roof and exterior carefully and show what the storm did, apart from age. Then we present that evidence to the insurer.
What do I pay, and how long will a storm claim take?
No money is due upfront. We take a percentage of the settlement, and a written contract spells it out before we start. Storm claims usually take at least 3 months.
Storm damage at home? Call us.
Tell us what the wind and rain did and where the insurer stands.
Washington Public Adjusters, 5015 Olympic Hwy, Aberdeen, WA 98520
matt@washington-publicadjusters.com · WA license # 1232824