Licensed in Washington · License # 1232824
Fallen Tree Damage Claims in Western Washington
A tree on your roof, siding or fence is rarely just the damage you can see. We work for you, not the insurer, to document all of it and press for a settlement that covers the real cost of repair.
Direct line to our Aberdeen, WA team: 360-300-7366
Open 24/7. Residential homeowners only. Nothing upfront.
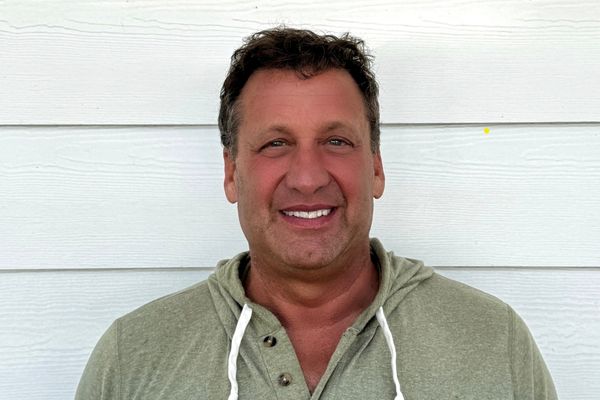
“We deal with the insurer, so you can focus on your home.”
Matt Hultman, Owner
- LicensedWashington license # 1232824.
- LocalLed by Matt Hultman, with a local Aberdeen, WA team.
- Nothing upfrontPaid a percentage of the settlement, under a written contract.
What we do for you on a fallen tree claim
Your insurer sends its own adjuster. We make sure your side of the claim is just as thorough.
We read your policy
We go through your coverage and everything your insurer has sent.
We find all the damage
We inspect the roof, the structure under it, the rooms below and the exterior, not only the visible hole.
We write the full claim
We document every item and put the complete cost of repair in writing.
We deal with the insurer
We submit the claim and negotiate with the adjuster, so you can focus on your home.
Open 24/7. Tell us what happened and we will take it from there.
Stuck with your insurer? Read what homeowners say about working with us.
G★★★★★5.0 from 12 Google reviews“I had a very positive experience working with Washington Public Adjusters… After months of going back and forth with our insurance company without any progress, we were feeling frustrated and stuck.”
Cynthia · Google review
Read Cynthia's review on Google“Excellent experience with Washington Public Adjusters, after a fire at my home Allstate gave me only 10% of what it was going to cost for repairs.”
Gretchen · Google review
Read Gretchen's review on Google“Matt at Washington Public Adjusters was amazing to work with. He really cares about his customers and not afraid to go the extra mile to get the job done.”
Christy · Google review
Read Christy's review on GoogleHow we help you get the money you deserve
An estimate usually covers what is easy to see. We look for what it leaves out.
What we find that the estimate misses
- Broken rafters, trusses and decking hidden under intact shingles
- Rain damage inside: insulation, ceilings, walls and floors
- Tree removal that is tied to the damage
- Siding or roofing that will not match what is left
How we get it paid
- We write the full claim and negotiate with your insurer's adjuster for you.
- Nothing upfront. We are paid a percentage of the settlement, under a written contract you sign first.
- Residential homeowners only. Claims usually take at least 3 months.
- Use a contractor from our trusted local directory, or your own.
How it works
A public adjuster works for you, not the insurer.
Call or request a review
Tell us what happened. We are open 24/7.
We document the loss
We inspect the property and record all of the damage.
We deal with the insurer
You sign a written contract first. Then we submit and negotiate for you.
Repair and settle
Claims usually take at least 3 months. Use our trusted local contractors or your own.
What a fallen tree claim usually includes
Every policy is different. These areas are commonly documented when a tree hits a home.
Roof and structure
Roof covering, decking, and the rafters or trusses beneath. Framing can crack out of sight.
Exterior
Siding, gutters, windows and doors, plus decks or porches the trunk or limbs struck.
Fences and outbuildings
Fences, sheds and detached garages, often covered under a different part of the policy.
Interior water and contents
Rain that enters after the hit, wet insulation, ceilings and floors, and damaged belongings.
Tree and debris removal
Removal from the structure is commonly treated differently from removal from the yard. It depends on your policy.
Temporary repairs
Tarping and board-up to stop further damage. Keep every receipt.
What to do in the first 24 to 48 hours
- Safety first. Leave any unstable area. Stay away from downed power lines and call your utility or 911.
- Photograph and video everything. Tree, roof, exterior and interior, wide and close, before anything is moved.
- Stop further damage. If it is safe, tarp the roof or board up openings. Keep the receipts.
- Keep damaged materials. Do not throw away broken shingles, siding or belongings until they have been documented.
- Report the claim. Note your claim number and the name of everyone you speak with.
- Do not sign contractor paperwork yet. It can commit you to a price and scope before the full damage is known. Talk to us first.
- Call us. We are open 24/7.
Why tree claims get underpaid
Hidden structural damage is missed
Broken rafters and decking cannot be seen from the ground.
Only the visible hole is estimated
The estimate covers the shingles at the impact and stops there.
Interior water damage is left off
Rain after the hit soaks insulation, ceilings and walls.
Tree removal limits are misunderstood
Structure and yard removal are often treated differently.
Matching is ignored
Whether matching applies depends on your policy.
Your tree or your neighbor's
Whose tree it was does not always settle who pays. If your own tree falls on your home, your homeowners policy is usually where the claim starts. If it is your neighbor's, your policy often still responds.
It depends on the policy and the circumstances, including the condition of the tree. Photograph where it stood and landed, and do not sign anything until you have talked to us.
Winter windstorms in Grays Harbor
Windstorms come off the Pacific every winter, and trees across Grays Harbor and Western Washington stand in wet ground that makes them easier to bring down. One storm can hit many homes at once.
Insurers and contractors get busy, so document early and protect the home from more rain.
Fallen tree claim questions
Does homeowners insurance cover a tree that falls on my house?
Often it does, when wind or a storm brought the tree down. It depends on your policy and the circumstances. We read your policy and tell you what applies.
Will my insurer pay to remove the tree?
It depends on your policy. Removing a tree from a damaged structure is commonly treated differently from clearing one that fell in the yard, and limits can apply. We check your wording and include removal tied to the damage.
A tree from my neighbor's yard fell on my home. Who pays?
It depends on the policy and the circumstances. Your own policy is often where the claim starts, even when the tree was your neighbor's. Photograph where it stood and landed, and call us before you sign anything.
Can a contractor start repairs before my insurer inspects?
A tarp or board-up is fine. Keep the receipts. For anything more, call us first, and keep damaged materials and photos before anything is torn out.
My insurer's estimate only covers the hole in the roof. Can you help?
Yes. This is a common problem. We inspect the structure under the roof, the rooms below and the exterior, document everything the tree and rain affected, and present the full repair.
What does it cost, and how long does a claim take?
Nothing upfront. We are paid a percentage of the settlement, under a written contract you sign first. Claims usually take at least 3 months. Use our directory of trusted local contractors, or your own.
Tree on your home? Call us.
Tell us what happened and what your insurer has said.
Washington Public Adjusters, 5015 Olympic Hwy, Aberdeen, WA 98520
matt@washington-publicadjusters.com · WA license # 1232824